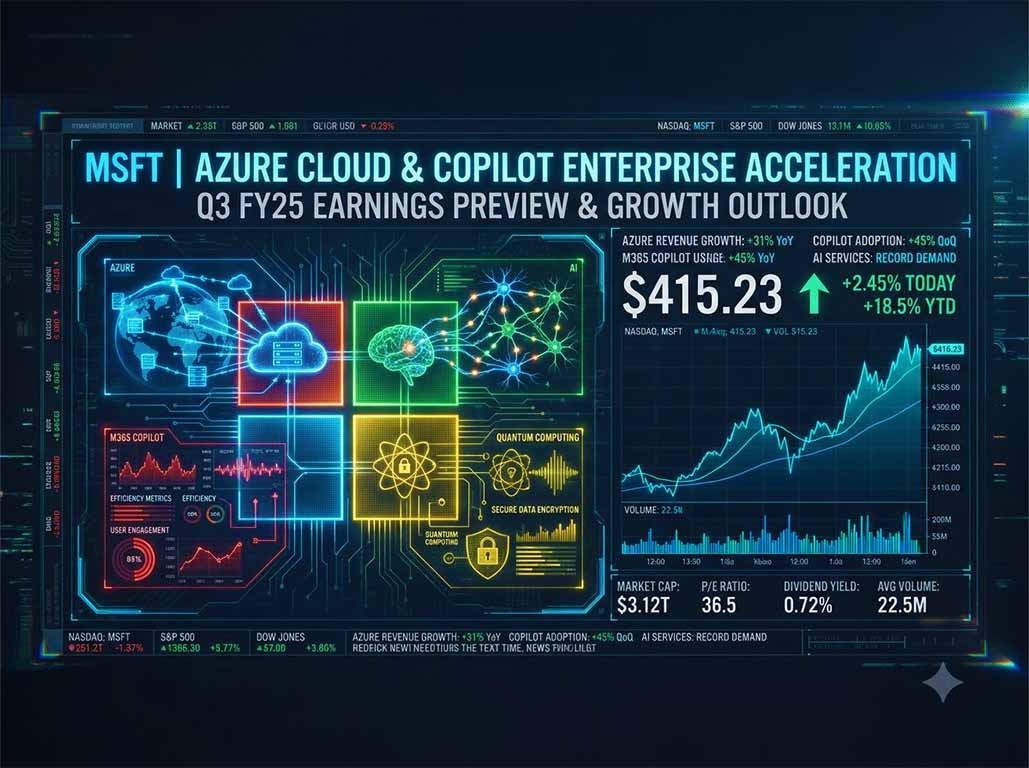
Evaluating MSFT Stock in 2026 highlights Microsoft’s structural dominance across global enterprise cloud infrastructure, productivity software, cybersecurity, and applied artificial intelligence. Microsoft Corporation (NASDAQ: MSFT) has successfully transitioned from early AI developer partnerships into high-margin enterprise commercial monetization. By embedding generative AI capabilities natively across its software ecosystem, Microsoft captures outsized market share while maintaining world-class operating margins and multi-billion-dollar free cash flow compounding.
1. Azure AI Infrastructure Drives Outsized Market Share Gains
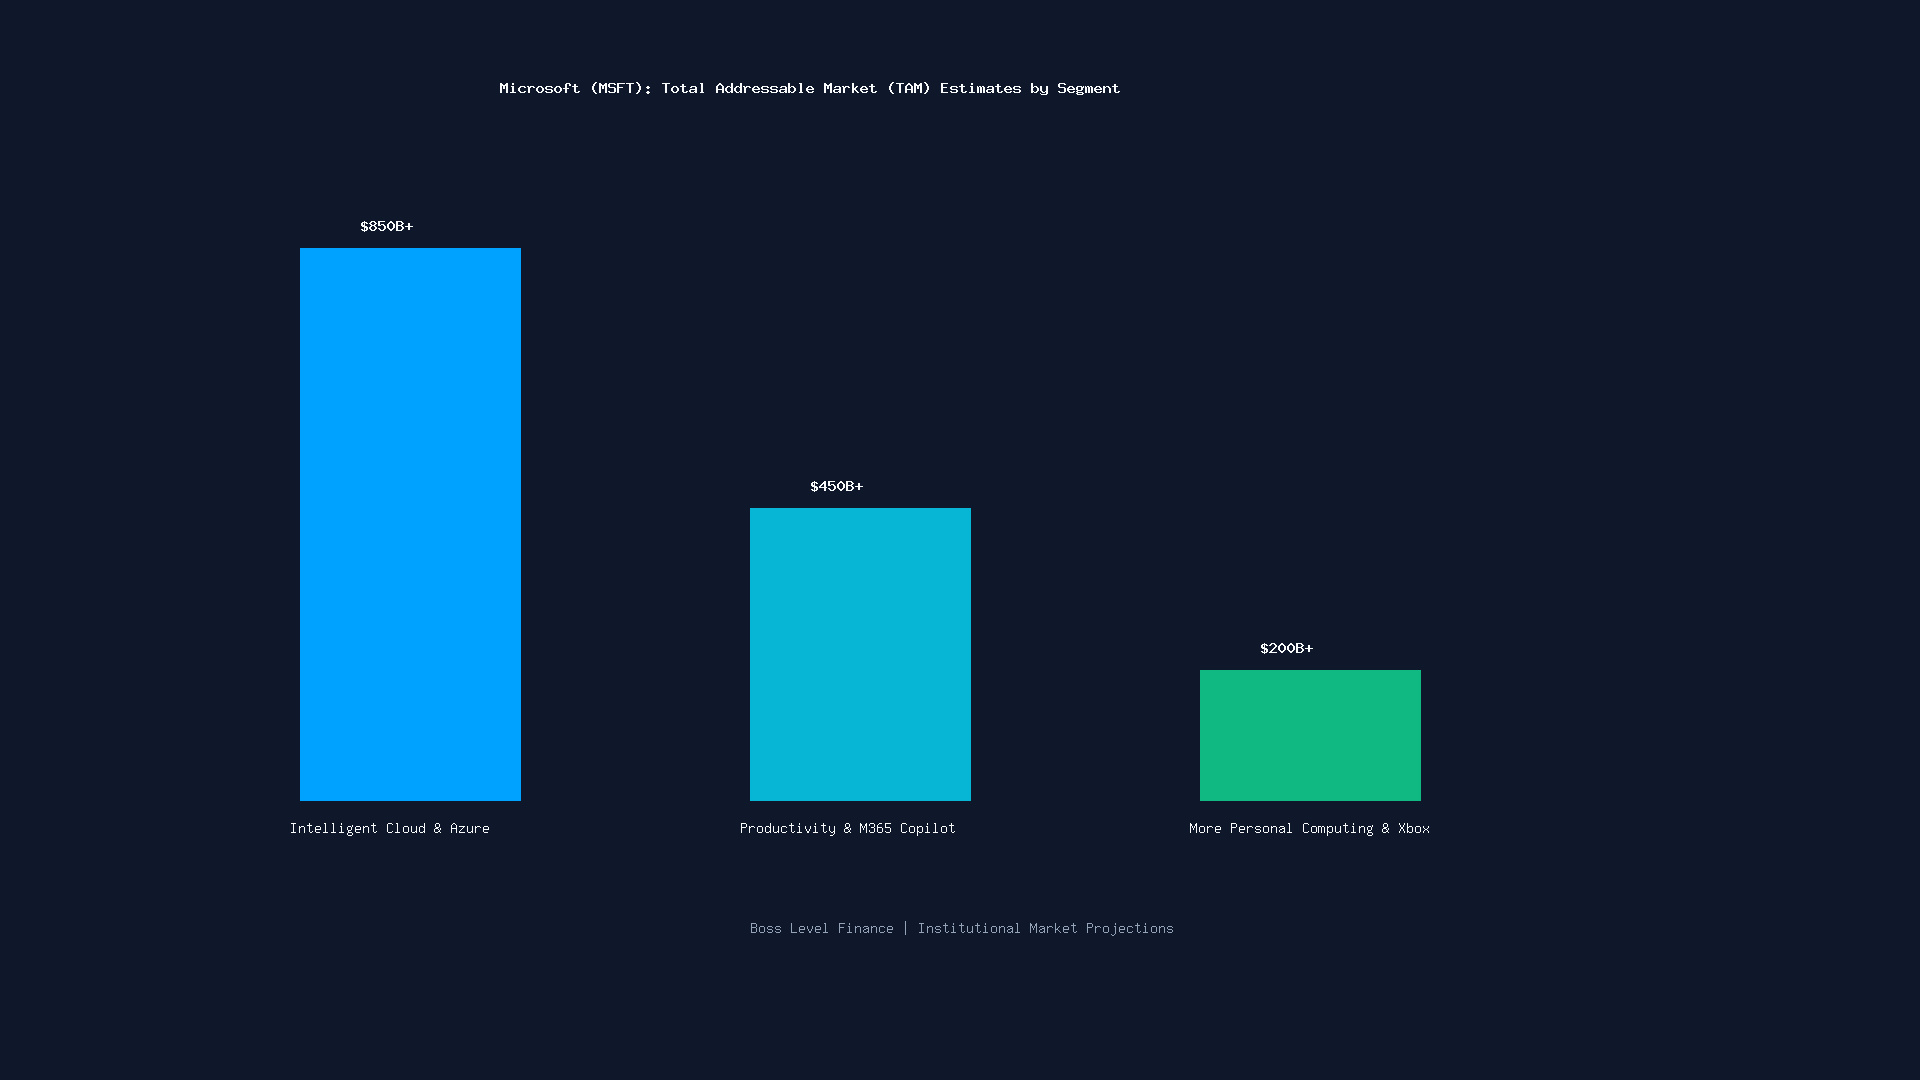
First and foremost, Azure Cloud revenue growth is heavily powered by native AI model integration and OpenAI GPT-4o enterprise hosting. Global enterprises choose Azure over competing public clouds because it offers seamless governance, data compliance, and direct integration with existing Active Directory security models. Rather than operating purely as a raw infrastructure provider, Azure provides end-to-end cognitive search, vector databases, and custom AI application development tools.
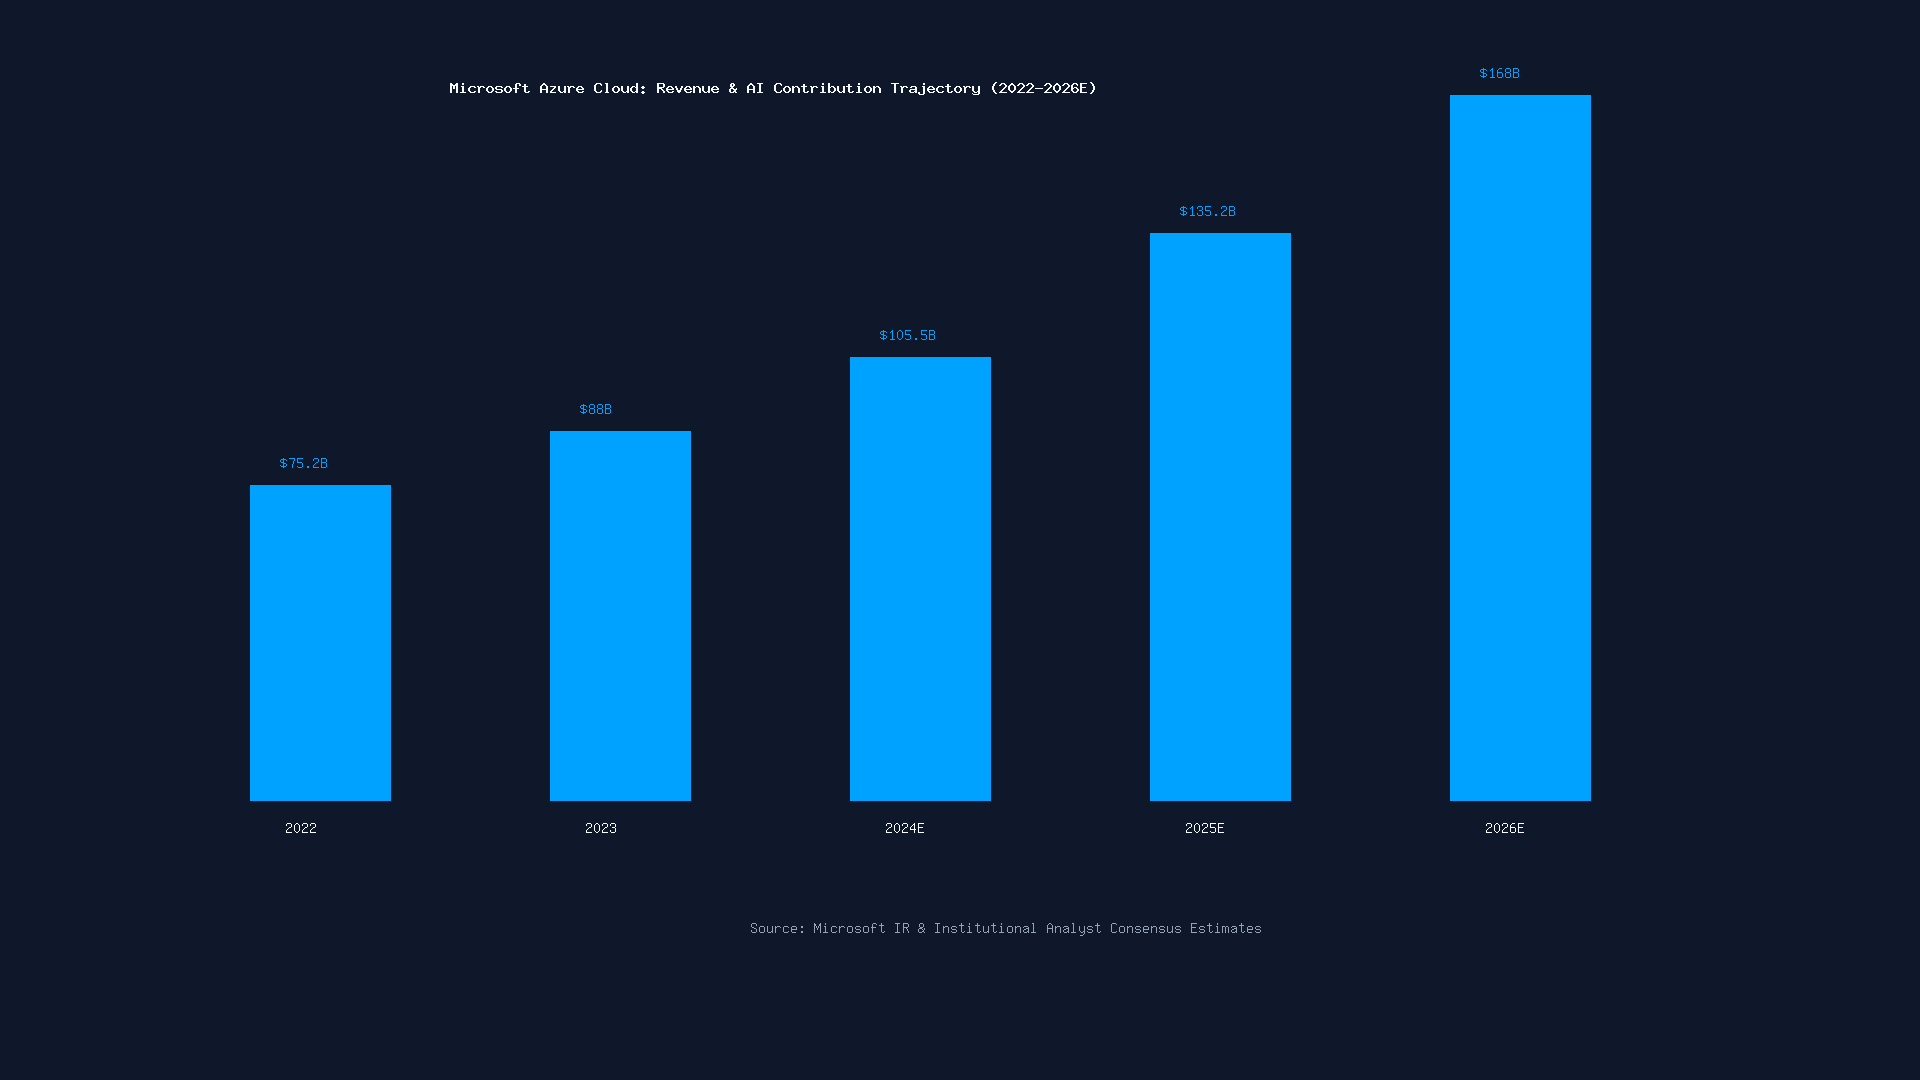
As Fortune 500 corporate IT departments shift capital from pilot testing into full-scale production deployment, Azure AI workloads are accelerating annual cloud revenue toward $168 Billion. Furthermore, Microsoft’s custom silicon strategy featuring Maia 100 AI accelerators and Cobalt 100 ARM-based CPUs’significantly lowers per-token inference compute costs. This custom hardware footprint protects overall Intelligent Cloud operating margins above 45%, insulating corporate earnings against elevated capital expenditure cycles.
2. MSFT 365 Copilot Commercial Adoption & ARR Expansion
Secondly, Microsoft 365 Copilot represents the fastest-monetized enterprise software add-on product in tech history. Priced at $30 per user monthly for commercial accounts, Copilot embeds generative AI capabilities natively into essential daily workflows across Word, Excel, PowerPoint, Outlook, Teams, and Power BI. This integration delivers measurable productivity gains by automating document generation, complex data modeling, and meeting synthesis.
With commercial seat adoption expanding rapidly beyond 35 Million paid enterprise users, Microsoft is expanding Average Revenue Per User (ARPU) across its existing commercial base of over 400 Million seats. This seat expansion creates a compounding stream of high-margin Annual Recurring Revenue (ARR) that flows directly to net operating income with minimal incremental distribution costs. Enterprise customers upgrading to E5 licensing tiers gain additional AI governance features, driving structural margin expansion.
3. Cybersecurity ARR & Unified Enterprise Platform Supremacy of MSFT
Beyond cloud computing and office productivity, Microsoft’s dedicated security organization spanning Defender, Sentinel, Entra, and Purview generates over $25 Billion in annual recurring revenue. Microsoft Security grows faster than standalone cybersecurity vendors because corporate Chief Information Security Officers (CISOs) prefer consolidating fragmented security vendor contracts onto Microsoft’s unified threat protection ecosystem.
By leveraging global threat telemetry gathered across billions of endpoints and daily authentication events, Security Copilot provides automated incident response and threat analysis. This unified software suite creates an impenetrable competitive moat, driving multi-product retention rates above 95% across global enterprise clients. Chief Technology Officers report up to 30% operational cost savings when consolidating security tooling under Microsoft E5 license agreements.
4. Financial Valuation, Cash Flow Compounding & Capital Allocation
From a capital allocation framework, Microsoft combines mega-cap balance sheet security with hyper-growth tech cash generation. Microsoft maintains a rare AAA credit rating “higher than the U.S. sovereign debt rating” backed by over $75 Billion in trailing twelve-month free cash flow. This fortress balance sheet allows Microsoft to aggressively fund AI data center CapEx while continuing its 20+ year streak of annual dividend increases.
Supported by steady cash flow from Windows OEM, LinkedIn commercial networking, and expanded gaming revenue following the Activision Blizzard integration, MSFT stock offers long-term growth investors an unmatched combination of downside valuation defense and top-tier AI enterprise exposure.
Institutional portfolio managers analyzing mega-cap tech compounders should also explore our comprehensive research deep dives on Tesla (TSLA Stock) AI & Energy Expansion, Meta Platforms (META Stock) AI Advertising Boom, Amazon (AMZN Stock) AWS Re-acceleration, and Broadcom (AVGO Stock) Custom Silicon Dominance.
💡 Further Reading for Investors:
Want to master growth stock valuations and competitive moats?
Check out
The Intelligent Investor by Benjamin Graham – https://amzn.to/4huFG8x
One Up On Wall Street by Peter Lynch – https://amzn.to/4huFLJn
The Psychology of Money by Morgan Housel – https://amzn.to/4fWa9d2
Principles for Navigating Big Debt Crises by Ray Dalio – https://amzn.to/4fZGTCl
Official Data & Reference Sources
- Microsoft Investor Relations Official Reports & Earnings Releases
- SEC EDGAR Official Corporate 10-Q & 10-K Filings
Furthermore, Microsoft’s intelligent cloud capital expenditures are directly backed by multi-year commercial customer commitments. The commercial backlog expanded by over 20% year-over-year, providing long-term revenue visibility across enterprise accounts. As cloud migration accelerates across healthcare, financial services, and public sector verticals, Microsoft’s diversified software portfolio remains resilient against macroeconomic headwinds.