
Analyzing AVGO Stock highlights Broadcom’s rare structural combination of high-growth custom AI semiconductor design and high-margin VMware enterprise software recurring cash flows. Broadcom Inc. (NASDAQ: AVGO) has positioned itself as the indispensable custom silicon backbone for hyperscale cloud data centers. Institutional investors evaluating AVGO stock in 2026 are focusing on compound dividend growth, expanding gross margins, and dominant custom ASIC market share.
1. Custom ASIC AI Silicon Surge for Hyperscale Cloud Giants
First and foremost, Broadcom’s custom XPU/ASIC silicon design business for tier-one cloud hyperscalers (including Alphabet Google TPU, Meta MTIA, and ByteDance) is expanding faster than merchant GPU solutions. As cloud architects seek to lower total cost of ownership (TCO) and reduce dependence on off-the-shelf accelerators, custom ASIC silicon demand has surged.
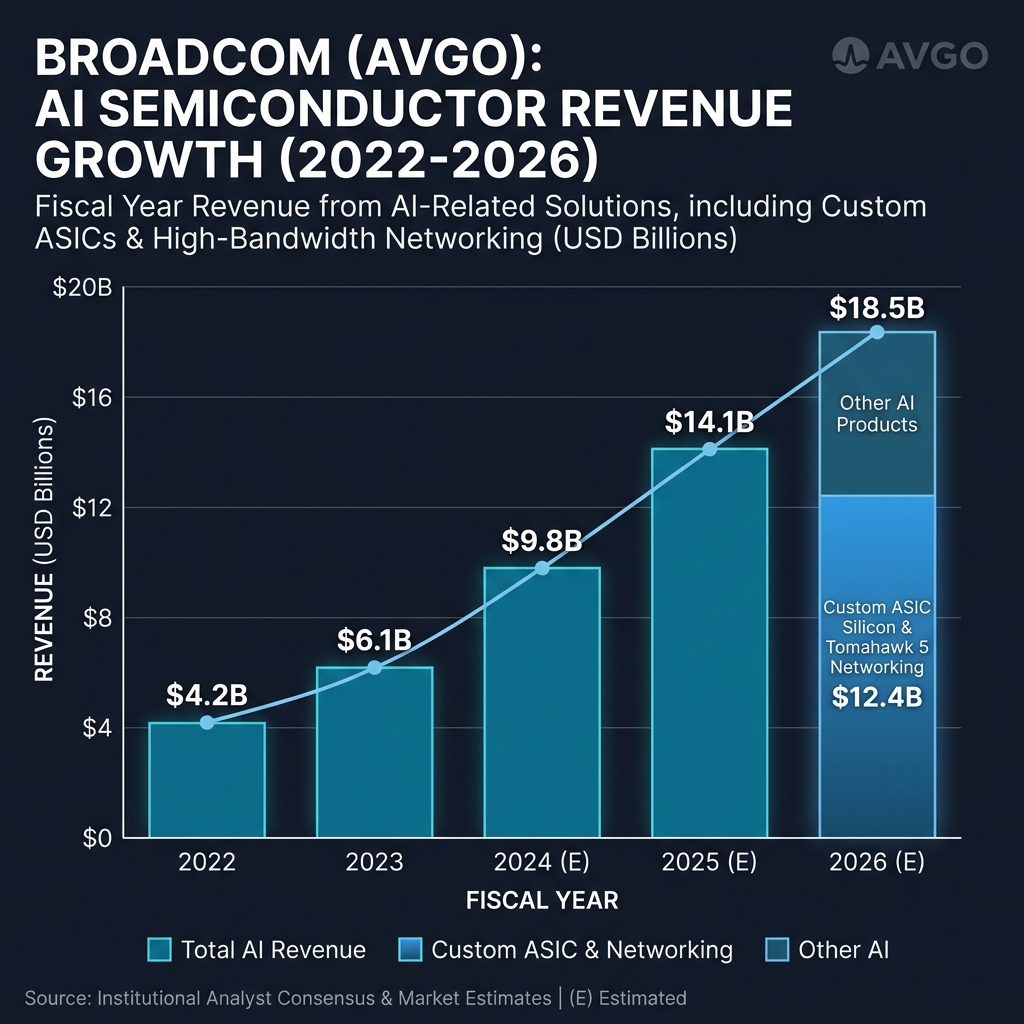
Broadcom’s deep IP portfolio in high-speed SerDes, co-packaged optics (CPO), and advanced packaging allows custom accelerator revenue to scale from $4.2B in 2022 to over $18.5B projected for 2026. This establishes Broadcom as the undisputed leader in custom AI silicon, capturing over 35% market share.
2. Tomahawk 5 & Jericho 3-X1 AI Ethernet Fabric Dominance
Secondly, high-performance AI clusters require ultra-low latency networking fabrics to interconnect tens of thousands of XPUs. Broadcom’s Tomahawk 5 switching silicon and Jericho 3-X1 fabrics lead the transition from proprietary InfiniBand to open, cost-effective Ethernet architectures.
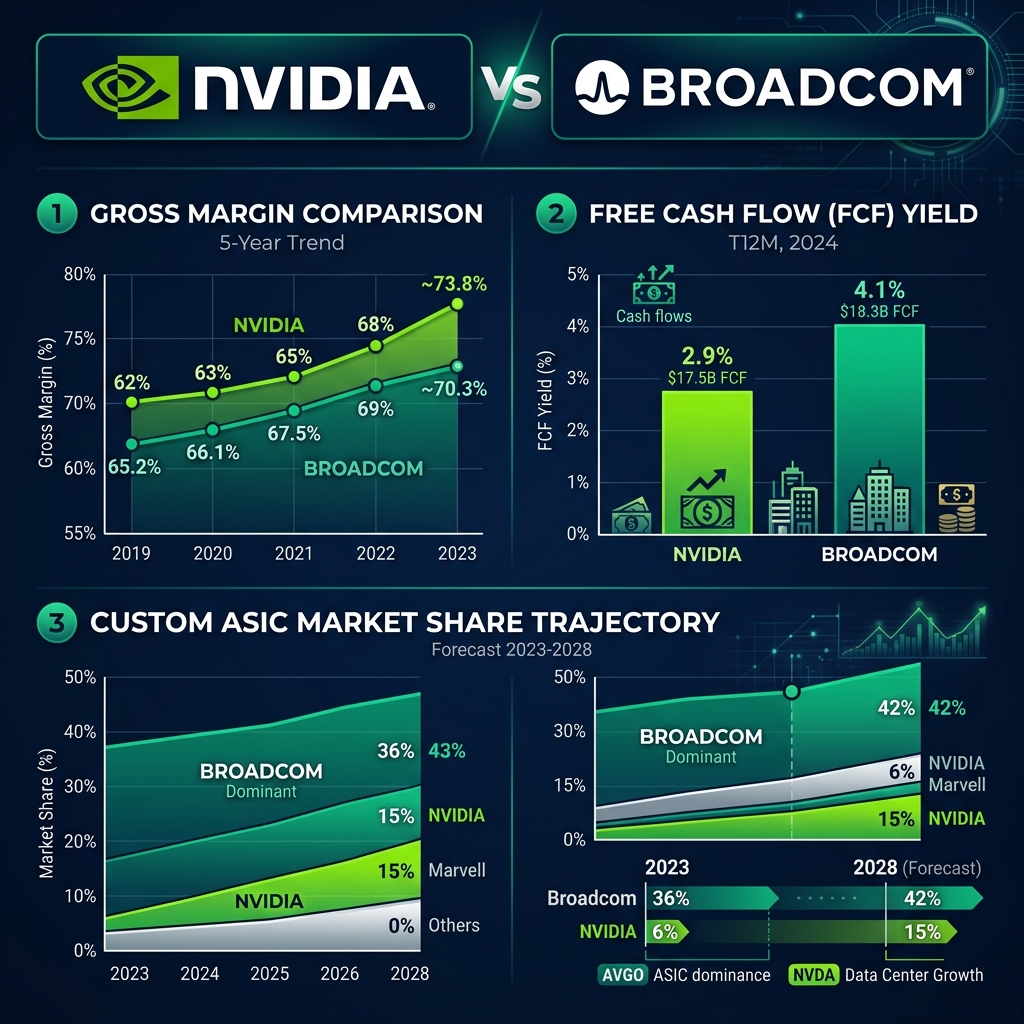
Because AI workload efficiency depends directly on network throughput, cloud operators upgrading to 800G and 1.6T Ethernet switches generate high-margin recurring silicon orders for Broadcom, protecting overall semiconductor gross margins above 70%.
3. VMware Integration Unlocks High-Margin Enterprise Cash Flow & Dividend Hikes
Beyond hardware, Broadcom’s acquisition and rapid restructuring of VMware into a private-cloud subscription licensing model provides predictable, multi-billion dollar software cash flows. Enterprise transition to VMware Cloud Foundation (VCF) subscription bundles drives operating margin expansion toward CEO Hock Tan’s 60%+ target.
With massive free cash flow generation ($18B+ annually), Broadcom maintains a strict commitment to returning 50% of trailing free cash flow to shareholders via annual dividend increases. For dividend growth investors, AVGO combines mega-cap compounding stability with AI hardware upside.
Investors analyzing semiconductor compounders should also read our deep dives on Tesla (TSLA Stock) AI & Energy Expansion and Meta Platforms (META Stock) AI Ad Growth.
💡 Further Reading for Investors:
Want to master growth stock valuations and competitive moats?
Check out
The Intelligent Investor by Benjamin Graham – https://amzn.to/4huFG8x
One Up On Wall Street by Peter Lynch – https://amzn.to/4huFLJn
The Psychology of Money by Morgan Housel – https://amzn.to/4fWa9d2
Principles for Navigating Big Debt Crises by Ray Dalio – https://amzn.to/4fZGTCl